AnswersCourt, and what comes after
Can I claim from a director personally for a company's unpaid invoice?
The short answer
Usually not. A limited company is legally separate from its owners1, so a supplier's bill is the company's debt2, not the director's. The exception to check first is a personal guarantee3: the director's promise to pay if the company does not. A spoken promise is not enough: a promise to pay someone else's debt must be in writing and signed by the person giving it4.
England and Wales only. WolfX is software, not a law firm.
The numbers
What to write on the file.
What you can add
An £8,640 bill and a signed promise
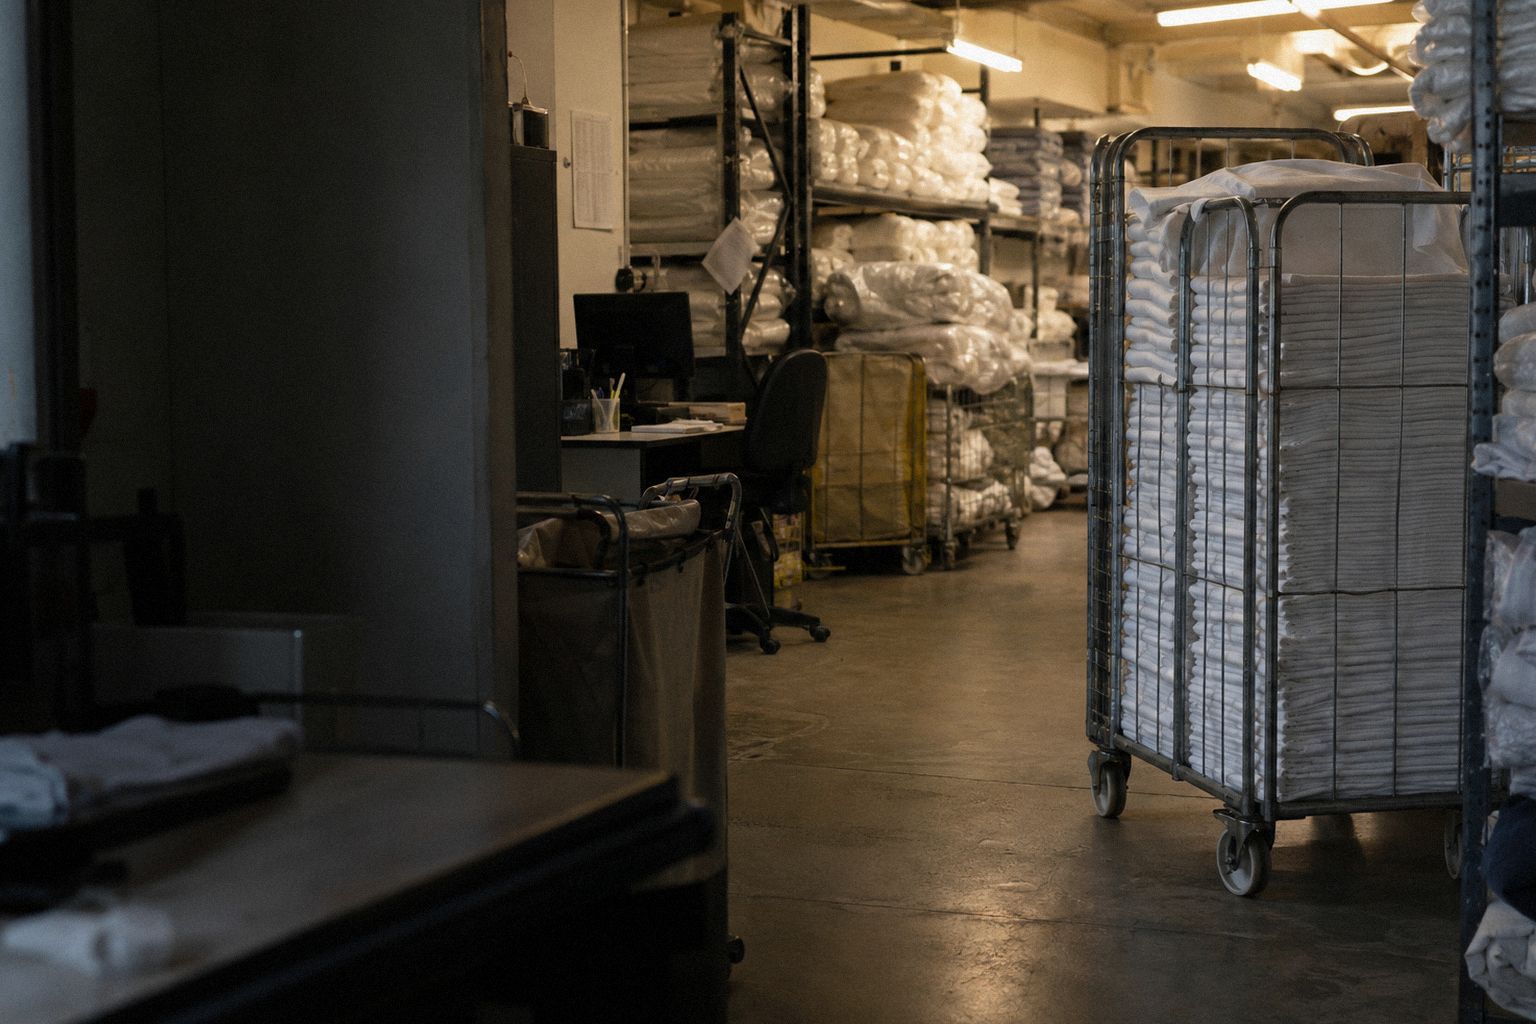
Say a restaurant company, formed in March 2026, owes you £8,640 on one invoice for three months of linen hire and laundry, due on 31 July 2026. Its director signed a personal guarantee in your credit application, with no cap. On 30 September the invoice is still unpaid: 61 days late. Interest uses the rate for invoices that went late between 1 July and 31 December 2026.
It grows by £2.78 a day until they pay. A claim for this sum sits in the £5,000.01 to £10,000 band: a £455 court fee10, with both names on the first claim form. With a personal guarantee, the director is a second person to claim from. Without one, the company is usually the only defendant.
The road ahead
Six steps. One court fee.
Step 1: Check whose name is on the deal
A debt taken on in the company's name is the company's; one taken out in a person's own name is theirs2. Check whose name is on your order, quote and invoice.
Then compare your order date with the date the company was formed, on its Companies House record. If it did not exist yet, section 51 of the Companies Act 20065 makes the person who acted for it personally liable, unless the contract says otherwise.
Step 3: Check it is in writing and signed
A spoken promise fails. Section 4 of the Statute of Frauds 16774 says a promise to pay someone else's debt cannot be sued on unless it, or a note of it, is in writing and signed by the person giving it or someone they authorised.
For an email, a text, unclear wording, or a claim that rests on what a director said or did, ask a solicitor who does commercial litigation. Nothing signed, and nothing in step 1? Stop: the debt is the company's.
Step 4: Read its limits and check the date
Read what the promise covers: which debt, any cap, any end date.
Under the Limitation Act 1980 a claim on an ordinary contract must start within six years9 of the day the right to claim 'accrued'. The Act does not say which day that is for a promise to pay someone else's debt. If the date is near, or the promise was made as a deed, ask a solicitor which limit applies.
Step 5: Send the director a Letter of Claim by post
Date the letter below at the top and post it that day or the next. Enclose the signed document, your invoice, a statement of account, and the Information Sheet, Reply Form and Financial Statement form from the Pre-Action Protocol for Debt Claims8.
When a business claims a debt from an individual, the court expects that protocol to be followed, with 30 days for the director to reply8. Send the company its own letter the same day.
Step 6: Name both in one claim
If 30 days pass with no payment or reply, start one claim against the company and the director. Rule 7.3 of the Civil Procedure Rules lets one claim form start every claim that can be conveniently decided together7.
The court fee is set by the size of the claim. Adding a defendant later costs £69 more, plus £126 or £321 to apply once the claim is served10. How to start it has its own page. Scotland and Northern Ireland use a different process.
A letter you can copy
Letter of Claim to a director who signed a personal guarantee
Send it only if you hold a personal guarantee, signed by the director, that covers this debt. Without one, write to the company instead.
Tap a highlighted gap to see what goes in it.
Post it on the day it is dated or the next, to the address the director gave on the signed document. Put your own address at the top and keep proof of posting. Claim only what the signed document covers. If it covers the invoice but not interest or the fixed sum, take those lines and the sentence about the 1998 Act out, and change the total. The protocol's Information Sheet, Reply Form and Financial Statement form are Annexes 1 and 2 of the protocol. Copy them from its PDF.
When not to bother
When it isn't worth it
- Nothing is signed and the company made the deal. The debt is the company's1, and so is any judgment, so chase the company. If it was struck off, see what that changes.
- The company is in liquidation and nothing is signed. Wrongful and fraudulent trading claims6 are the liquidator's, not yours. Claim in the liquidation instead.
- The director has little to pay with. A signed promise is worth only what the person can pay, so the claim has the same problem as a claim on a company with no money. Weigh that first, before you post the letter.
- The director has started a new company. The rules on re-using a name6 can make a person responsible for the new company's debts, not the old one's. Your bill stays with the old company.
The Wolf's note
A debt follows the name on the paper. Find the page with the director's signature before you write to anyone: with a personal guarantee, one claim carries two names; without one, the company is the whole claim.
Mr. Wolf · the AI inside WolfX
What comes next
Your next move
How do I take a company to court for an unpaid invoice?
Send a letter before action, then claim online.
7 min read · Letter included
Is it worth suing a company that has no money?
Only if it owns something you can take.
7 min read · Letter included
Before you chase
How do I check a new client can pay before I start work?
Only partly. Ten minutes on the free records shows who a client is, not whether it will pay.
6 min read · Letter included
Don't want to do this yourself?
The Wolf does every step for you. He works out the sums, writes the letters and keeps track of every date. Nothing goes without your yes.